Agency MBS

Prepayment analysis for agency MBS

Collateral and prepayment analysis across pass-throughs, on proprietary models trained on loan-level data.

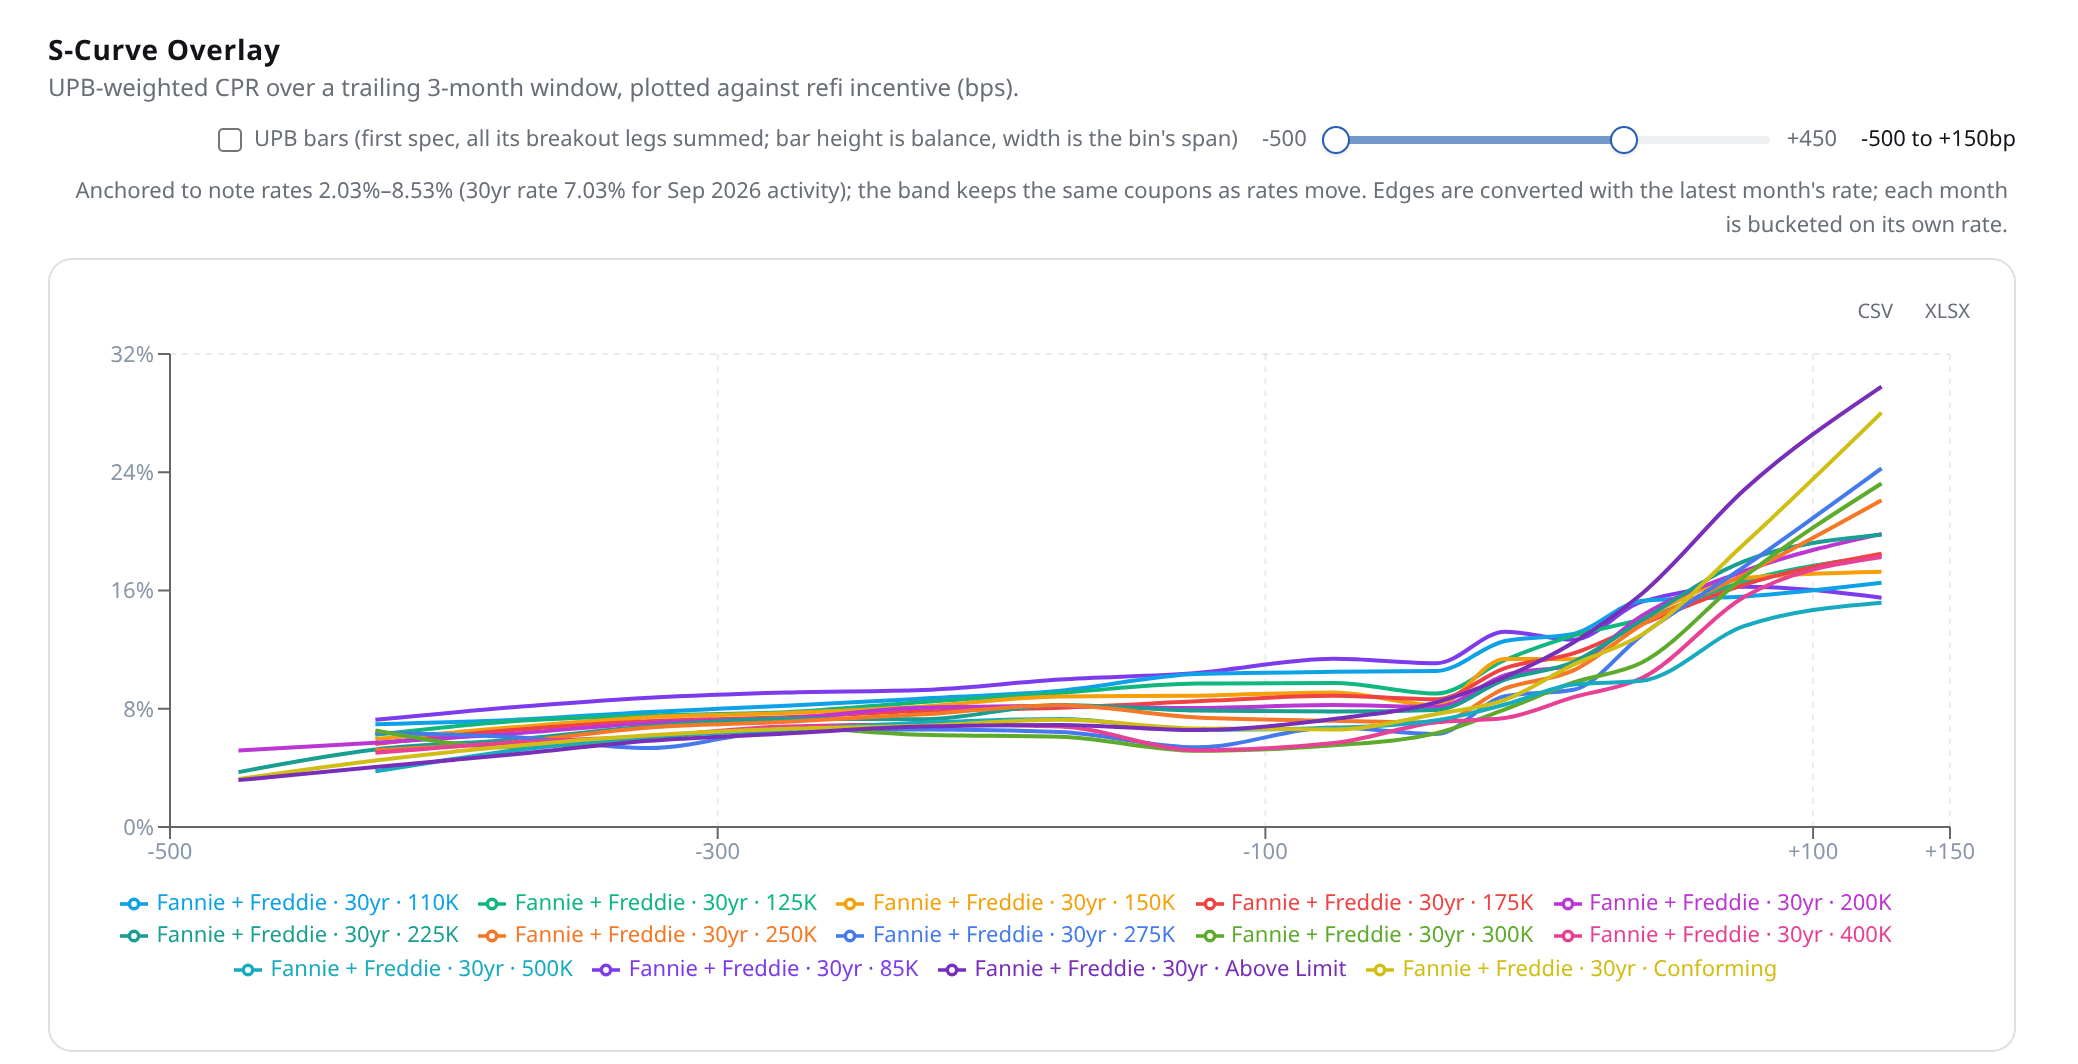
Oasive S-curve overlay: Fannie Mae and Freddie Mac 30-year prepayment speeds against refinancing incentive, broken out by loan size

Relative value in agency MBS

Pool screening and relative value by collateral.

01

Loan-level prepayment models

Proprietary models trained on loan-level data, with each projected speed broken into its components.

02

Pool screening and relative value

Screen pools and compare relative value by collateral, with S-curves by agency, coupon and cohort.

03

Portfolio risk

Portfolio risk and scenario analysis.

04

Custom research

Custom research for your book.

Who it’s for: Agency MBS PMs, traders and analysts, and the risk teams that work with them.

Questions

What goes into the prepayment model?
Agency loan-level data, so speeds reflect borrower and loan characteristics rather than pool averages alone. Each projection is broken into its components.
How do I compare pools?
By collateral, agency, coupon and cohort, with S-curves for each.
What market data is included?
Issuance, speeds and holdings by banks, the Fed, dealers, funds and foreign investors.
How much does it cost?
Pricing is set with each team, with enterprise-grade data governance and white-glove onboarding. Request a demo below.

More from Oasive

Talk to the team

Tell us what you cover. We reply within one business day.

Or email hello@oasive.ai